


Governor Abbott’s August 3, 2026 order to pause new data center grid interconnections landed like a change order on an already complicated job. For South Texas contractors, the question is not whether data center construction will happen-it will. The question is when, and what you do with your crews, your bids, and your cash in the meantime.
Key Takeaways
The i 35 industrial construction outlook shifted materially in August 2026 when the state froze new data center interconnections for audit. Here is what matters most for contractors in San Antonio and the broader South Texas footprint:
- Roughly 20% of the U.S. data center pipeline-close to 49.8 GW of capacity-is now at risk of delay, with Texas absorbing the largest share of that exposure because ERCOT’s interconnection queue holds approximately 474 GW in requests, about 90% of which are data center-related.
- South Texas contractors along the I-35 and I-10 corridors face schedule slides of 6–18 months on power-heavy digital infrastructure projects, not mass cancellations. The risk is to manpower loading, prefab timing, and cash flow-not to the pipeline itself.
- Industrial demand in central Texas, north Texas, and south Texas remains strong across advanced manufacturing, logistics, energy, and defense. The issue is backlog quality: the gross pipeline looks healthy, while the executable backlog may be thinner than it appears.
- Estimators, PMs, and executives must re-score active pursuits, tighten go/no-go criteria, adjust escalation assumptions, and coordinate procurement with realistic utility timelines.
- ABC South Texas provides market intelligence, apprenticeship programs, safety training, and advocacy resources that help member firms navigate the upcoming challenges with discipline rather than panic.
1. Fast Answer: How the Texas Data Center Pause Resets the I-35 Industrial Construction Outlook
On August 3, 2026, Governor Greg Abbott ordered ERCOT to pause all new data center grid interconnection reviews. The directive triggered a comprehensive audit of every project advancing through the queue, with regulators verifying on-site generation plans, water consumption, and whether developers are leveraging state or federal incentives. Texas is the fastest-growing digital infrastructure market in North America, and the order hit the industry’s largest growth corridor head-on.
BloombergNEF estimates that roughly 49.8 GW of U.S. data center capacity is exposed to delay risk-and a significant share of that sits in Texas. ERCOT’s interconnection queue totals approximately 474 GW, with about 90% of new power requests coming from data centers. The potential revenue impact is staggering: BNEF projects up to $8 billion in lost data center leasing revenue by Q1 2027 if 60% of delayed capacity is AI-related.
For the i 35 industrial construction outlook, this translates to timing shocks. Industrial real estate and digital infrastructure along the Austin–San Antonio corridor will not see mass cancellations-but commissioning schedules, power availability, and project sequencing are now uncertain. The central business question for every South Texas contractor: how do you protect margin, manpower, and backlog quality if high-profile data center expansion and digital infrastructure projects slip 6–18 months?
2. I-35 Corridor Snapshot: Industrial and Digital Infrastructure Between Austin and San Antonio
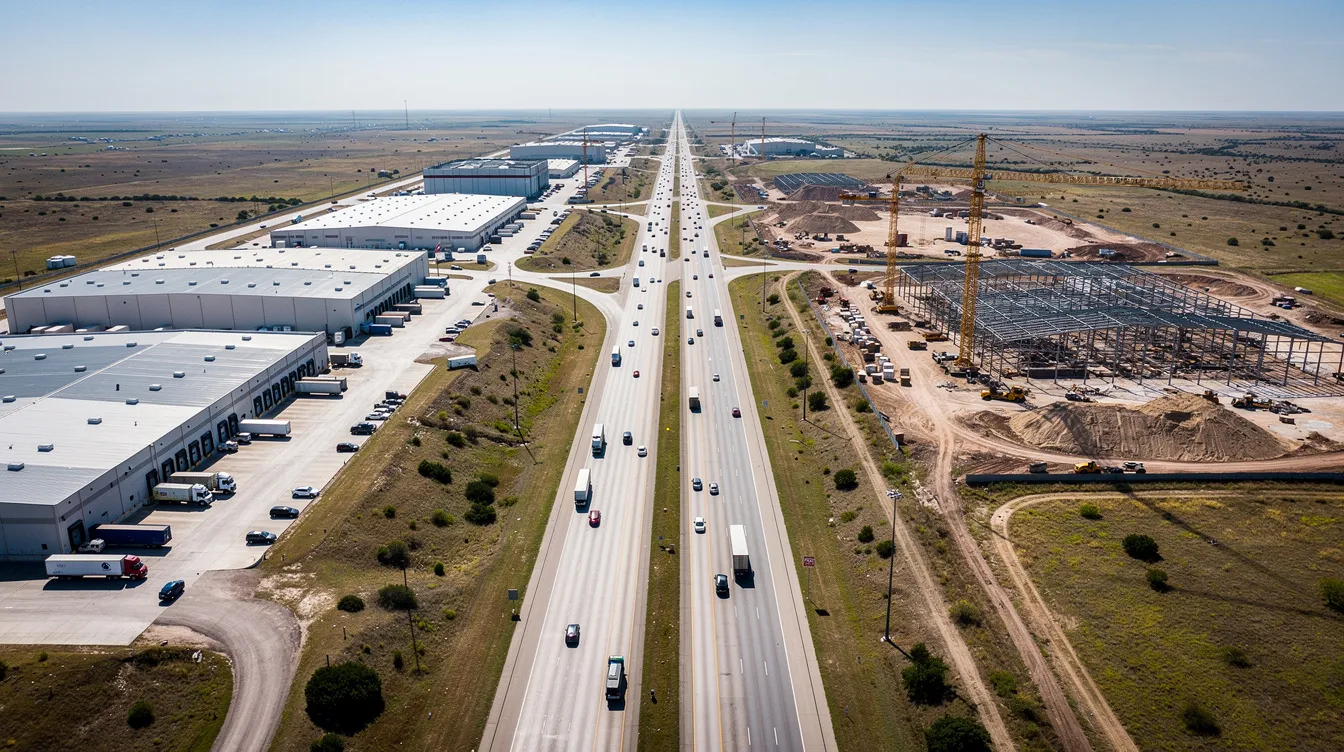
The I-35 corridor from North Texas through Central Texas to South Texas functions as a blended industrial base of logistics, advanced manufacturing, and data centers. The corridor represents nearly half of Texas’ gross domestic product and supports a large share of the state’s manufacturing, transportation, and warehousing activity. Locations near I-35 are attractive for companies seeking U.S.-based production capacity, and the focus has shifted from generic warehousing to high-tech industrial uses and advanced manufacturing.
Key data points that define the corridor right now:
- Samsung is investing $95 billion in the Taylor Hutto area north of Austin, anchoring a semiconductor supply chain that pulls industrial investment south toward San Antonio.
- 76 million square feet of industrial projects are underway in Dallas–Fort Worth, with spillover demand pushing into central Texas submarkets.
- Submarkets north and south of Austin are driving significant net absorption of industrial space, while the I-35 corridor is characterized by targeted recalibration and growth in secondary submarkets-places like New Braunfels and Medina County.
- Industrial construction along the I-35 corridor is positioned for significant growth over the next decade, primarily driven by e-commerce, nearshoring from Mexico, and population growth in Texas metros.
- Major metros like Austin and San Antonio have elevated overall vacancy rates, but net absorption remains positive in purpose-built industrial categories including cold storage, data center construction, and advanced manufacturing space.
Readers looking for a broader statewide view can find additional context in the Texas construction outlook 2026 analysis. This article zeroes in on the i 35 industrial construction outlook and data center timing risk specifically.
3. Texas Data Center Pause: What Exactly Changed and Where the Risk Sits
Governor Abbott’s August 2026 directive orders a verification and audit of all data center projects in ERCOT’s interconnection process. The review focuses on whether projects comply with June 2026 criteria: data centers must pay for their own infrastructure, add generation capacity, use water-efficient cooling, and not shift costs to ratepayers. High regional growth has strained local resources like water availability and environmental compliance, making these requirements more than symbolic.
Here is where the numbers stand:
- An estimated $64 billion in data center projects have been blocked or delayed nationally.
- ERCOT’s queue includes roughly 474 GW in requests, with data centers representing about 90% of new large-load applications.
- Only about 6 GW of large-load projects are currently observed drawing power-meaning the vast majority of queued capacity is still speculative or pre-energization.
- 142 activist groups are organizing against data center construction across the U.S., with Virginia alone hosting 42 activist groups opposing data center development. Data center projects face local opposition primarily at the permitting level, and a $100 million data center project was canceled after local political backlash in another state. Notably, 55% of politicians opposing data centers are Republicans, reflecting community opposition that cuts across party lines.
The critical distinction for Texas contractors: the pause affects interconnection approvals, not construction permits. Owners can still move dirt, pour foundations, and erect shells-but they cannot energize. Commissioning schedules for AI data centers and power-heavy industrial plants near San Antonio are now uncertain even where local permitting is supportive.
4. Who Is Most Exposed Along I-35: Trades, Scopes, and Industrial Segments
The Texas data center pause creates uneven exposure. Not every contractor or trade along the I-35 corridor faces the same risk.
Most exposed scopes and trades:
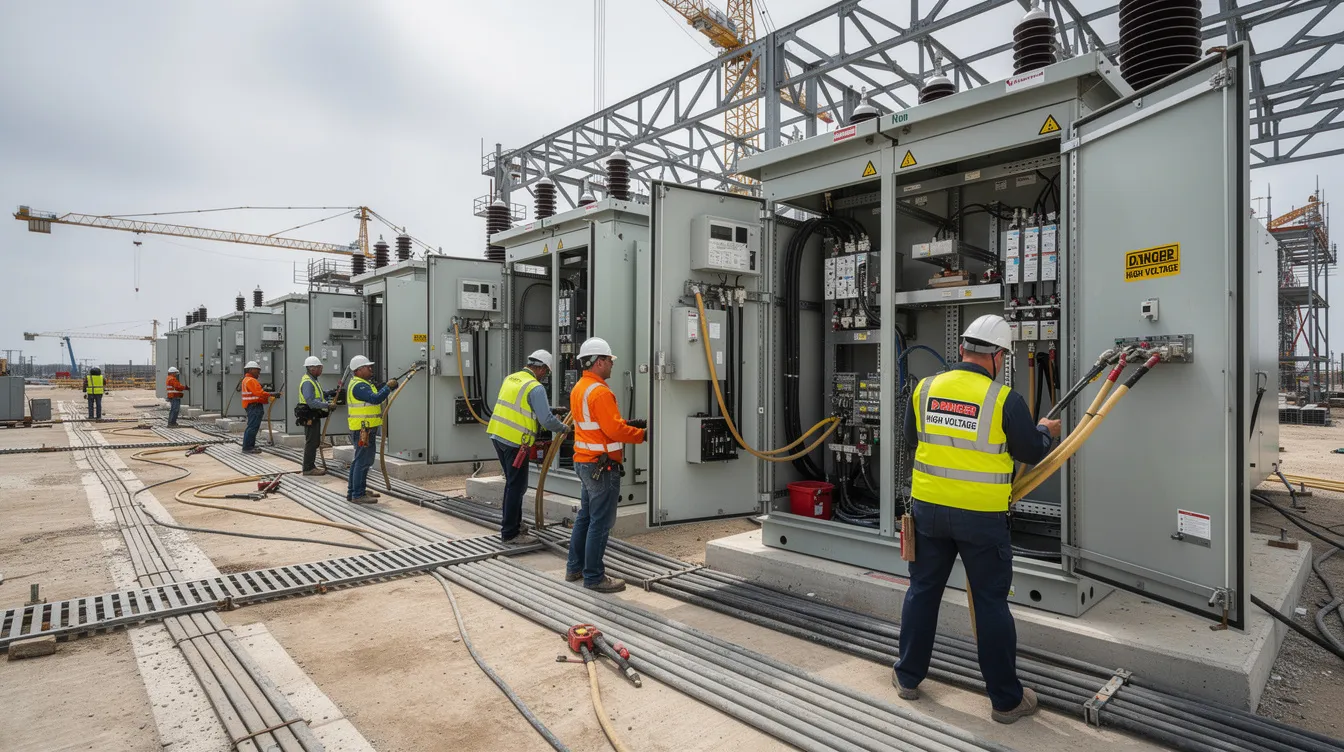
- Electrical contractors handling medium- and high-voltage work, substations, and UPS systems face the sharpest timeline risk-these scopes cannot commission without grid power.
- Mechanical and sheet metal contractors building cooling plants, chiller systems, and air handling for data centers and advanced manufacturing facilities.
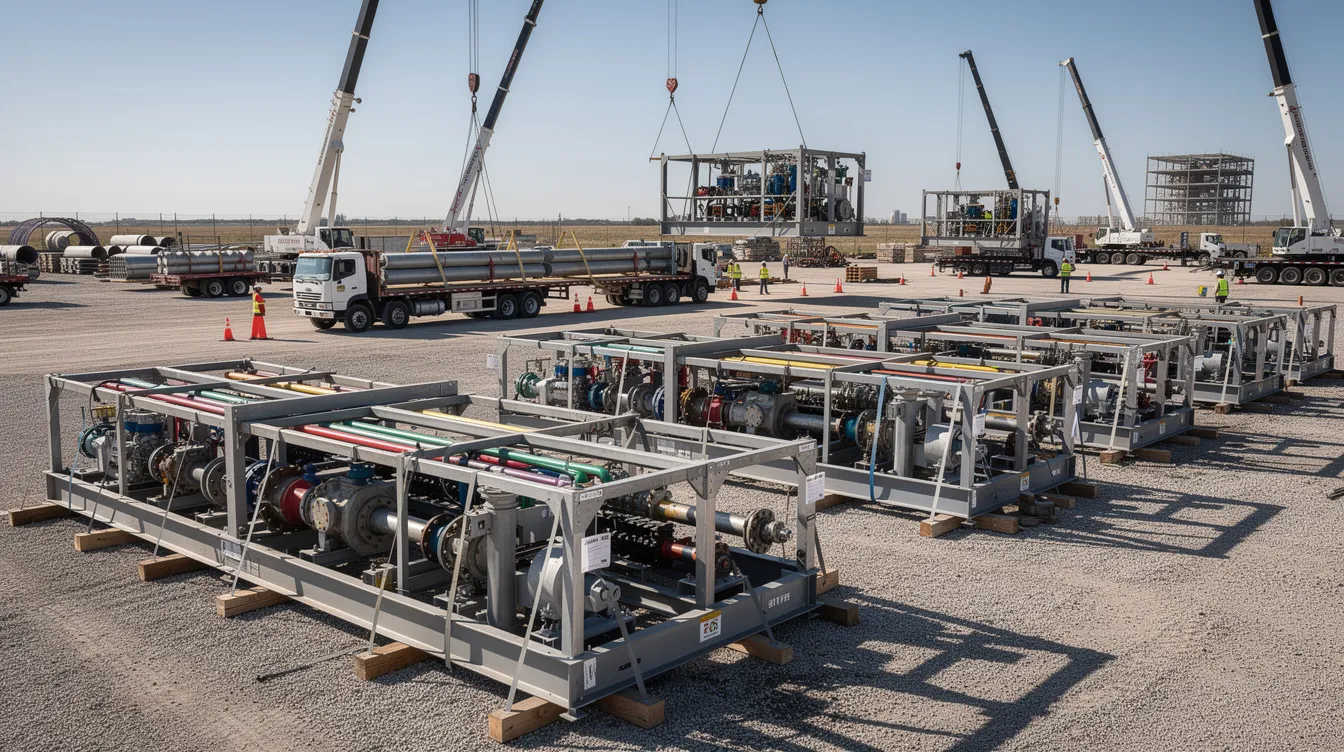
- Pipefitters working on chilled-water loops, fuel systems, and process piping tied to energization milestones.
- Civil and sitework firms on greenfield data campuses in Medina County and along the I-35 corridor may see extended dry-in periods.
- Specialty controls and low-voltage integrators whose work sequences after power is live.
Texas needs tens of thousands of additional electricians by 2026, and electrical apprenticeship enrollment in San Antonio grew 18% from 2023 to 2025-but the construction industry faces a skilled labor shortage due to retirements that compounds the scheduling problem. Texas construction labor markets remain exceptionally tight with low unemployment rates, meaning you cannot simply staff up when a stalled project restarts.
General contractors whose 2026–2027 backlogs are heavy with single-site data center or digital infrastructure projects near Austin or San Antonio will see the biggest impact. Industrial contractors with diversified work across manufacturing, distribution, healthcare, and public-sector projects can reassign craft more easily.
5. Bid Strategy Under Uncertainty: How Estimators Should Adjust Now
The Texas data center pause changes risk allocation in contracts. Owners, developers, utilities, and large tech tenants will attempt to push more schedule and escalation risk down to the construction team. Estimators who do not adjust now will absorb costs that belong elsewhere.
Specific bid-strategy moves for South Texas estimators:
- Require clearer milestone and energization assumptions in RFIs. Do not accept a baseline schedule built on optimistic target dates for power availability.
- Include explicit qualifications around ERCOT approvals, substation readiness, and utility timelines in every proposal for data center and power-heavy industrial work.
- Adjust contingencies for long-lead electrical gear, generators, and transformers-items with 12–18 month lead times that can sit in storage if interconnection slips.
- Revisit escalation and overtime assumptions for late-2026 and 2027 starts, particularly for labor-intensive electrical and mechanical packages.
- Overall ground-up speculative construction pipelines have pulled back compared to peak years, and elevated borrowing costs and tightened lending standards have curtailed speculative land plays. Factor this into pursuit volume expectations.
The Dallas–fort worth area led the nation in industrial permits in late october 2025, and Texas’s industrial construction market is driven by e-commerce demand-but bid-hit ratios can look good on paper while real revenue quality falls if contractors chase delayed work too aggressively. The difference between gross backlog and executable backlog is the difference between a forecast and a paycheck. The construction backlog in 2026 analysis covers this distinction in detail.
Estimators should coordinate tightly with project executives and procurement to model schedule slips and their impact on prefab shop loading, equipment rentals, and crew continuity.
6. Backlog Discipline and Cash Flow: Reading the I-35 Industrial Pipeline Correctly
In a high-demand environment like Texas, the 2026 risk is not a shortage of opportunities-it is a backlog stacked with new projects whose start dates depend on grid and policy milestones outside the contractor’s control.
How to re-score your backlog:
- Classify every data center and digital infrastructure project pursuit by interconnection status. Does the project have an executed interconnection agreement? Is the owner’s funding committed? Is the tenant identified?
- Separate projects in San Antonio, Austin, and North Texas into tiers: approved to energize, study-backed, and speculative queue position.
- Texas is expected to deliver fewer than 50 million square feet of warehouse space in 2026-a significant decrease from recent years-which means the broader industrial real estate market is also recalibrating, not just data centers.
- Contractors must sequence utility relocations and drainage tunneling before constructing surface structures on many I-35 industrial sites; delayed utility work compounds the schedule risk from interconnection pauses.
Cash flow implications are serious. Delayed NTPs and stretched commissioning push out revenue recognition, increase under-absorbed overhead, strain lines of credit, and delay retainage collections by 6–12 months on large I-35 industrial jobs. Firms whose backlog is rich in paper-pipeline data centers will see margin risk if those items do not convert.
For firms managing capital timing, the construction tax deductions analysis offers relevant planning context.
7. Sequencing, Manpower, and Prefabrication: Field-Level Impacts in 2026
The macro signal-a statewide data center pause-translates into micro decisions: when to ramp crews, release materials, and load prefab shops for I-35 industrial construction projects.
What field leaders should expect:
- Sudden stop–start cycles on data campus interiors as interconnection timelines shift.
- Extended dry-in periods while waiting on power gear, with shells complete but no energization date.
- Compressed commissioning windows once approvals come through, creating overtime and safety pressure.
- Freight traffic is expected to increase by 41% over the coming decades along the I-35 corridor, and massive public infrastructure expansions often create logistical hurdles for developers working in the same geography. Major highway investments are expected to improve access and encourage additional construction, but they also compete for the same labor pool.
Prefabrication timing is critical. Stage MEP racks, skids, and switchgear enclosures to allow for storage and re-sequencing if energization dates move. The risk of overbuilding prefab components before design and utility timelines are firm is real-and expensive.
Rapid industrial growth in Texas is putting pressure on energy and water infrastructure, compounding the scheduling complexity for contractors running multiple sites. Investing in training programs can help develop younger workers’ skills to handle this volatility, and raising salaries can attract younger workers to the construction trades-both necessary moves in a market with tremendous growth ahead but uncertain timing.
The construction hiring what record low labor churn means analysis provides additional context on workforce planning. ABC South Texas apprenticeship programs in electrical, pipefitting, sheet metal, plumbing, and carpentry give member firms a bench that can flex across project types when schedules shift.
8. Alternative and Adjacent Work: Where South Texas Capacity Can Go If Data Centers Slip
The i 35 industrial construction outlook remains fundamentally strong because Texas’ industrial base is diversified. The surge in data center construction is one piece of a broader expansion story.
Where to redirect capacity:
- Port San Antonio redevelopment and defense-related projects tied to Joint Base San Antonio offer steady, funded scopes for contractors with security clearances and industrial capability.
- Regional healthcare facility construction, school bond programs, and city infrastructure work absorb skilled craft across electrical, mechanical, plumbing, and carpentry trades.
- Smaller industrial real estate builds-20,000 to 200,000 square feet warehouses, light manufacturing, and logistics facilities-continue to move forward because they are below the 75 MW threshold that triggers ERCOT’s large-load process.
- Texas’s construction pipeline includes $185 million for natural gas processing and related energy facility work that is independent of the data center interconnection pause.
- Grid and power work unrelated to paused data center interconnections-distribution upgrades, on-site generation, and microgrids serving industrial users along I-35 and I-10-represents a growing market segment.
For contractors with a footprint in Dallas–fort worth or austin, balancing workloads between delayed data center interiors and ongoing semiconductor, logistics, or public-infrastructure work is the practical path forward. The I-35 corridor industrial construction analysis covers trade strain and multi-market juggling in more depth.
This is about absorbing capacity and protecting crews in the coming years-not chasing speculative narratives about the next big thing.
9. Contracts, Risk Transfer, and Owner Communications Along the Corridor
Under current uncertainty, contract language and upfront communication with owners and developers along the I-35 corridor matter as much as the bid number itself.
Contract and negotiation items to revisit:
- Escalation clauses tied to long-lead electrical and mechanical equipment must reflect realistic delivery windows, not pre-pause assumptions.
- Build in allowances or contingencies for utility-driven delays, and include clear force majeure or “regulatory change” provisions that address the evolving ERCOT policy landscape.
- Base baseline schedules on verified utility milestones rather than optimistic target dates, particularly for AI data centers and high-load industrial plants.
- Proactive communication with owners about ERCOT timelines, local permitting status, and manpower availability reduces adversarial disputes when delays occur. Owners and city officials who understand the constraints are more likely to negotiate schedule relief rather than enforce liquidated damages.
Ethical contracting promotes merit shop principles in construction, and merit shop principles prioritize open bidding and competition-values that become more important, not less, when market uncertainty tempts some parties toward risk-shifting or non-transparent practices. Ethical practices in construction enhance community engagement and advocacy, strengthening the contractor’s position in negotiations.
This article does not constitute legal advice. Consult counsel on specific contract provisions and use ABC South Texas resources for market and risk-education support.
10. Safety, Workforce, and Merit Shop Advantages in a Volatile I-35 Market
In a period of schedule volatility and tight labor markets, contractors who keep crews trained, safe, and consistently employed across shifting project types along I-35 and I-10 hold a competitive edge over those who treat workforce as a variable cost.
- Safety training reduces workplace accidents by 30%, and effective safety training can lower insurance costs by 25%-margin protection that matters more when project schedules are uncertain.
- OSHA mandates safety training for all construction workers, and training programs must be updated annually to meet regulations. Over 60% of construction firms prioritize safety training, but the firms that treat it as a strategic investment rather than a compliance checkbox outperform when crews move between fast-paced data centers and heavy industrial jobs with different risk profiles.
- ABC South Texas advocates for ethical contracting in the construction industry, and training programs support ethical contracting and workforce development across the chapter’s 22-county footprint.
- Record-low labor churn makes it harder to staff up quickly when a paused project suddenly gets the green light. Firms with stable, NCCER-accredited apprentices in electrical, pipefitting, sheet metal, plumbing, and carpentry can respond faster and price less overtime risk into their bids.
- STEP participation, OSHA 10/30 certification, and VitalCog programming are not just checkboxes-they are the infrastructure that lets a merit shop contractor compete on performance when the market rewards execution over speculation.
11. Next Moves for South Texas Contractors: A 30-Day Action Checklist
Do not wait for the market to clarify itself. Here is a 30-day playbook for executives, estimators, and project managers across San Antonio and the broader 22-county footprint.
Week 1–2:
- Re-score every active pursuit involving data center, power-heavy industrial, or digital infrastructure work. Flag any project without a confirmed interconnection agreement or committed owner funding.
- Verify ERCOT status on your top 10 pipeline projects. If the development team cannot confirm interconnection progress, downgrade the pursuit’s probability.
- Tighten internal go/no-go criteria to require verified utility timelines and owner capital commitment before investing significant bid overhead.
Week 2–3:
- Update standard bid qualifications to address power and permitting uncertainty. Add explicit language around ERCOT approvals, substation readiness, and energization milestones.
- Review contingency assumptions for all 2026–2027 work. Adjust for interest rates, material escalation, and potential overtime on compressed commissioning windows.
- Schedule an internal meeting between estimating, operations, finance, and safety leaders to align manpower, prefabrication capacity, and risk appetite for I-35 and I-10 corridor work over the next four quarters.
Week 3–4:
- Evaluate apprenticeship enrollment for key trades-electrical and pipefitting are the focal point given data center and industrial demand. Contact ABC South Texas to review current enrollment windows.
- Engage with ABC South Texas chapter communications on policy and market updates. Monitor developments in ERCOT’s Batch Zero process and gubernatorial directives moving forward.
Treat this reset as an opportunity to upgrade your risk management and backlog discipline-not just a problem to endure. The contractors who price uncertainty now, rather than absorbing it later, will come out of 2026 with stronger margins, better backlogs, and crews that are ready to mobilize when the grid clears.
FAQ
These FAQs address practical questions South Texas contractors may have after reviewing the i 35 industrial construction outlook, covering items not fully detailed above.
How long could the Texas data center interconnection pause realistically last?
Official timelines are still evolving as of late 2026. ERCOT’s Batch Zero process was adopted in July 2026, but the governor’s August audit adds another layer of review. Contractors should plan for interconnection approvals to extend by 6–18 months beyond original expected dates. Watch official ERCOT and state releases rather than relying on developer optimism or industry rumors. Projects with mature documentation and site control will likely clear faster than speculative queue entries.
Does the pause affect smaller industrial users along I-35, or only hyperscale data centers?
The current regulatory focus is on large, power-intensive data centers and AI data centers-specifically loads of 75 MW or greater under the Batch Zero framework. However, grid constraints and utility reprioritization can indirectly affect mid-size industrial users. A new 5–20 MW manufacturing plant or logistics hub may face delays if local substations are capacity-constrained by queued data center load, even though the facility itself is not subject to the pause.
What signals should contractors track to know if a specific data center project is likely to move forward?
Watch for executed power contracts, filed and approved interconnection agreements, notice-to-proceed on civil work, evidence of long-lead equipment orders (transformers, generators, switchgear), and owner communications about internal funding or tenant commitments. Projects that cannot demonstrate these markers are speculative regardless of how large the announced square feet or investment figures appear.
How can smaller subcontractors protect themselves when bidding on paused or high-risk digital infrastructure work?
Insist on clear payment terms and milestone-based billing. Limit exposure to unpaid change orders tied to utility delays. Avoid overconcentration of backlog in a single project or owner. Negotiate for mobilization and demobilization reimbursement if power-related delays exceed a defined threshold. Engage with trade associations like ABC South Texas for best practices on contract language and risk management in a volatile market.
Where can ABC South Texas members get ongoing updates about the Texas industrial market and policy changes?
Members should monitor ABC South Texas news and market briefings, including the Texas construction outlook 2026 coverage and the I-35 corridor industrial construction analysis. Stay engaged with chapter events, committees, and alerts focused on regulatory and market shifts. The chapter’s safety, workforce, and government affairs programming provides a practical edge for firms navigating the evolving landscape of Texas industrial construction through the rise and development of the next decade.


